

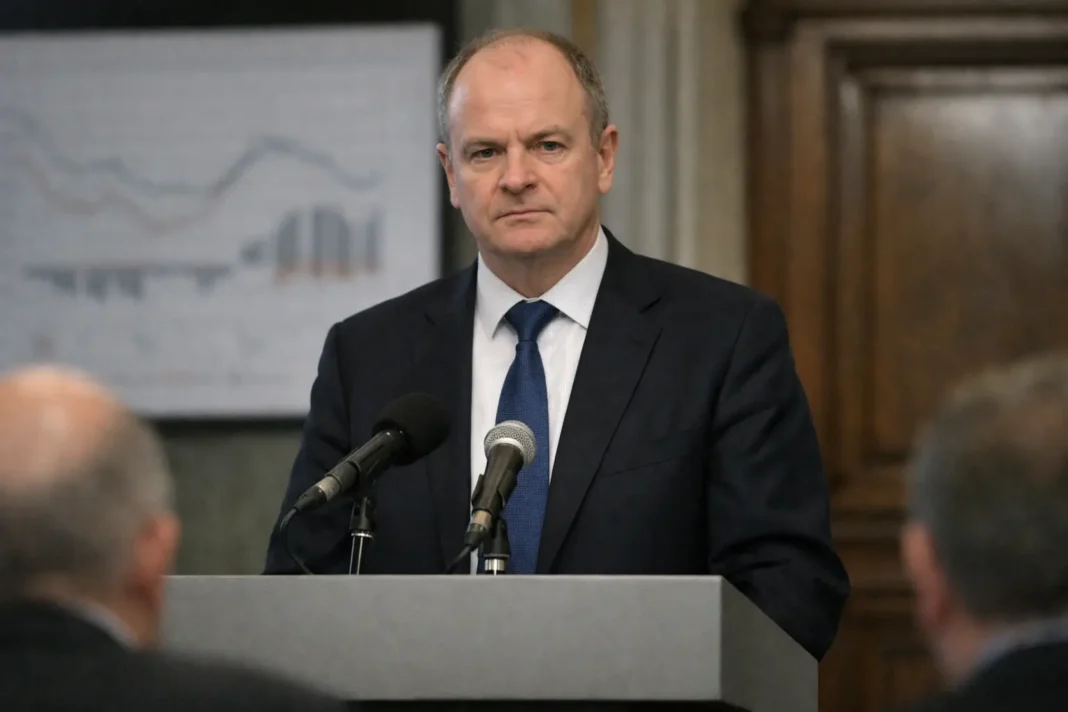
Britain’s borrowing costs may rise again in the coming months after Huw Pill, chief economist at the Bank of England, indicated that monetary policy has not yet reached the level needed to contain persistent inflation. His comments follow this month’s decision to lift Bank Rate from 3.75% to 4%, a move that marked another tightening step as policymakers try to bring price growth under control.
Pill described the latest increase as an important adjustment but made clear that officials may still have additional work ahead. The direction he outlined points to a possible rise next month and another in early 2027, keeping pressure on households and businesses already facing higher financing costs. The signal matters because the Bank’s rate-setting path influences mortgage pricing, consumer credit, savings returns and corporate investment decisions across the UK economy.
The most immediate impact would be felt by borrowers whose fixed-rate mortgage deals are due to expire. An estimated 2.3 million homeowners are expected to refinance in 2027, exposing many to higher monthly repayments if market rates remain elevated or rise further. That refinancing wave has become a key channel through which monetary policy affects household budgets, especially for families moving from older deals agreed when borrowing costs were significantly lower.
For the Bank of England, the policy challenge is to curb inflation without placing unnecessary strain on growth. Higher interest rates can cool demand by making loans more expensive and encouraging saving, but the effects arrive with a delay. That creates a difficult balance for rate-setters: acting too slowly risks allowing price pressures to become embedded, while moving too aggressively can weaken consumption, investment and confidence.
Pill’s remarks underline that the central bank remains focused on inflation despite the growing burden on mortgage holders. Financial markets, lenders and households will now watch the next policy meetings closely for confirmation of how far the tightening cycle may still run. With Bank Rate already at 4%, even small additional increases would carry significant consequences for mortgages, consumer spending and business planning into 2027.